
If you want to see why servicing is important today, you just need to look at Stratmor’s recent survey of lenders, particularly which areas are most important to those who are currently subservicing: homeowner experience, cost effectiveness and technology/innovation.
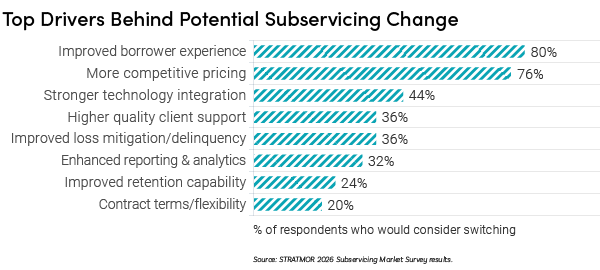
That’s not a coincidence. These three areas are the opportunity right now. Specifically for mortgage, these are some of the areas where servicing has not received the level of investment that origination has comparatively.
Not coincidentally, they are where we’ve been heavily focused at Cenlar. They, along with compliance expertise, are where a subservicing partner can bring the most value to lenders. It’s a cost-conscious, plug-and-play solution.
Unless you are a massive lender, you can’t afford to keep up with the latest technology or homeowner experience innovations or the constantly changing regulatory compliance landscape. And you definitely can’t spin up the kind of expertise you get on day one with a subservicer.
The Big Four
No. 1: The homeowner experience. Customer relationships are more important than ever. Servicing provides you with an ability, as a lender, to establish a relationship between origination cycles. A superior customer experience provides constant reinforcement so it’s easier to retain the relationship.
This was a huge takeaway from research released by American Banker in August: most financial institutions are missing a prime opportunity to grow their business with the data they get from their homeowners.
Servicing is a data business. Servicers have years of data, every interaction, payment, loan modification. They are data points that create a larger picture of homeowner and portfolio trends.
Subservicers that know how to interpret that data for you can provide a huge advantage in considering how to strengthen homeowner engagement and relationship retention opportunities.
No. 2: Technology and innovation. To be able to do all of that, you need to have the technology.
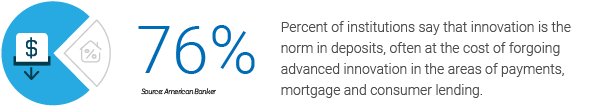
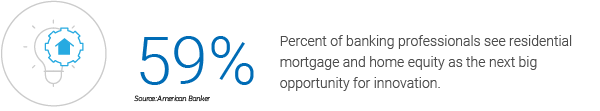
Despite this, financial institutions are not adopting generative AI and developing real-time data capabilities as quickly as they believe they should be. Mortgage servicing offers a prime opportunity, in particular.
AI and automation has been our focus at Cenlar over the last few years. Subservicing gives you access to that emerging technology.
At Cenlar, we innovate so our clients can focus their energy and money on growing their business.
No. 3: Cost efficiency and scalability. Servicing requires a wide range of expertise: customer service, compliance, investor relations, loss mitigation. This kind of talent isn’t common or cheap.
No. 4: Built-In compliance expertise. Regulatory compliance is one of the biggest expenses and pain points of in-house servicing. Complexity is rising, and you can’t afford to get it wrong. Servicing is at the front line of this. A subservicer can support much of the burden by managing day-to-day compliance.
What To Look for in a Good Partner
If you decide to explore subservicing, you need to be very intentional about what you need. You are selecting a partner, not a vendor.
Start with defining your goals and understanding theirs. Are you headed in the same direction?
Like any relationship, success will depend on shared values and clear communication. Your subservicer will be flag bearers for your brand. Who will treat your business and your homeowners as their own?
The right subservicer will share their expertise and act as advisors for your business. At Cenlar, we’re partners who look out for the best interests of our clients and our industry. We publish thought leadership on Cenlar.com, including a results-based blog series and a series of infographics that show how we’re combining our expertise with innovation to tackle the issues that matter most in servicing.
We do this because a key part of our culture is building long-term relationships. We have been servicing loans since the 1960s and invented subservicing as we know it today. We signed our first subservicing agreement nearly 40 years ago and have several clients who have been with us for nearly three decades.
As you can see, a subservicing relationship can be for the long haul, and it’s important for lenders to make the right decision for them. With the right partner, subservicing offers scalable technology, compliance expertise and data insights that improve homeowner satisfaction and influence things like refinance and origination.
Many financial institutions have made this decision, handing the servicing function to an expert and allocating resources to priorities that grow their business.
Or, as we like to say at Cenlar, we allow our client partners to manage less and gain more.